Ready for More Space? A Guide for Move-Up Buyers
Real Estate By Jean
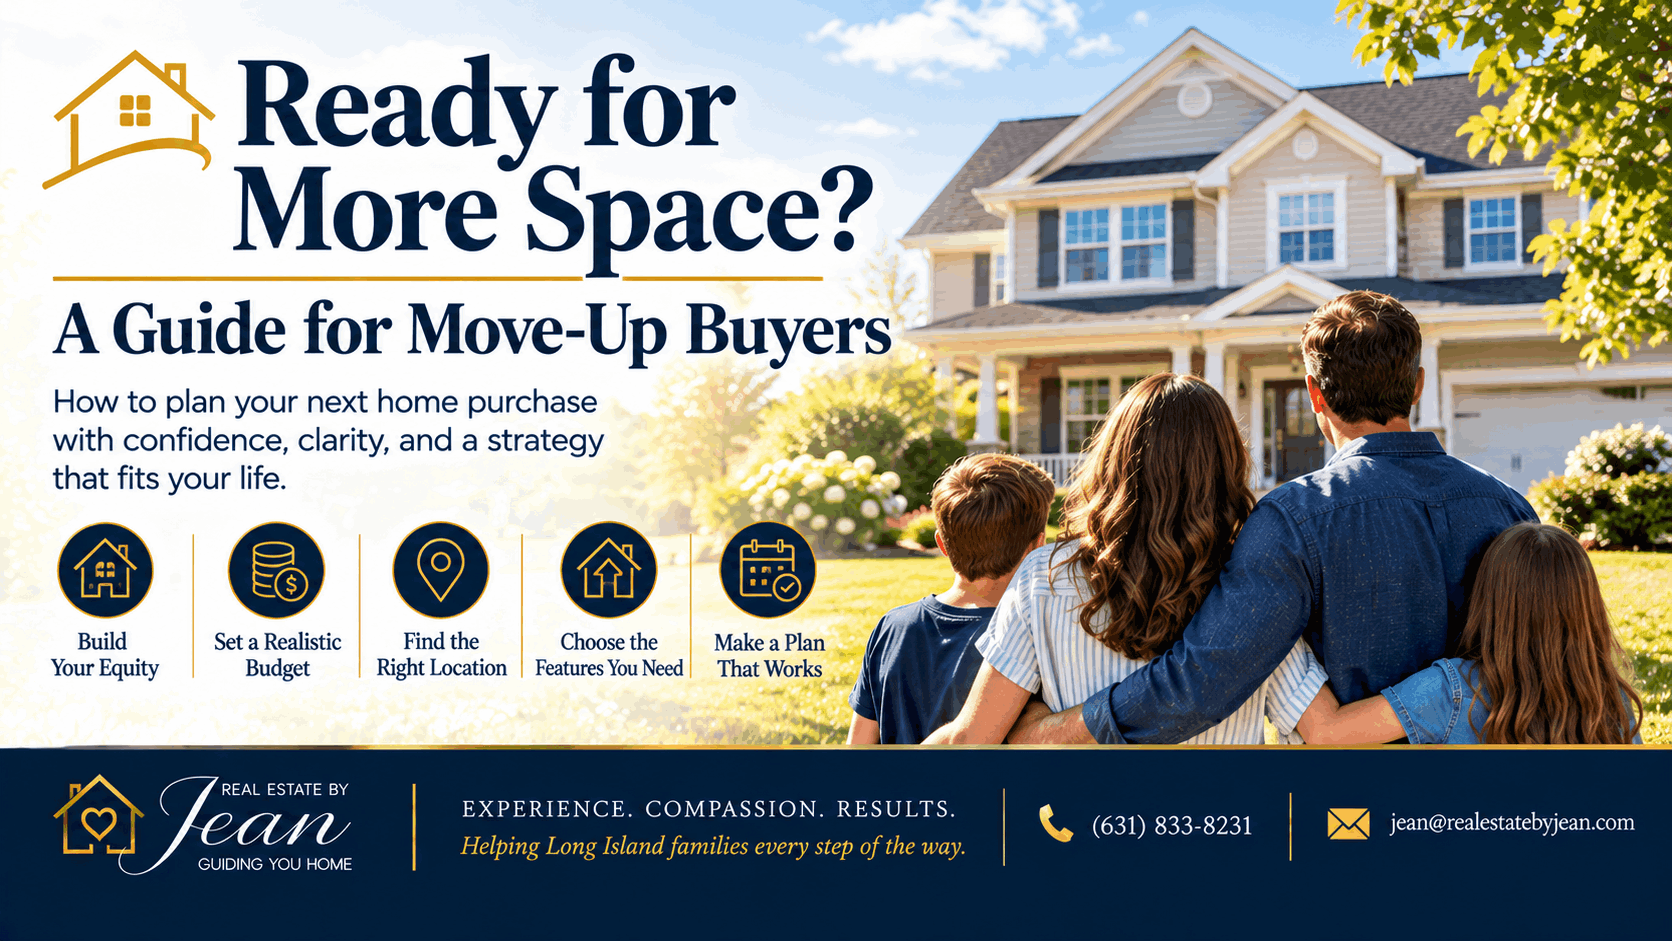
Ready for More Space?
A Guide for Move Up Buyers
How to plan your next home purchase with confidence, clarity, and a strategy that fits your life.
Your current home may have been the perfect fit when you bought it. But life changes, and sometimes the home that once met all your needs begins to feel a little too small.
Maybe your family has grown. Perhaps you need a home office, more storage, a larger kitchen, or a backyard where everyone can gather. You may simply be ready for a different layout or a neighborhood that better fits your next chapter.
Moving into a larger home can be exciting, but it also involves important financial and logistical decisions. You need to consider what your current home may sell for, how much you can comfortably spend, and whether to sell before buying or coordinate both transactions.
With a clear plan, you can explore your options and make a move that supports both your current needs and your long term goals.
Moving up is not just about buying a bigger house. It is about finding a home that fits the life you are building next.
1. Recognize When Your Current Home No Longer Fits
Before looking at new listings, take time to identify what is missing from your current home. Understanding your reasons for moving will help you focus on properties that solve real problems rather than simply offer more square footage.
Common Reasons Homeowners Move Up
- A growing family needs additional bedrooms or living areas.
- Working from home requires a dedicated office.
- The current layout no longer supports everyday routines.
- Storage, parking, or outdoor space has become a challenge.
- You want a different neighborhood, school district, or commute.
- You are ready for features that were outside your budget when you purchased your current home.
Write down your three most important reasons for moving. Use those priorities to guide your search and help you decide which features are worth paying more for.
2. Find Out How Much Equity You Have
Your current home may be one of your most important financial resources when buying your next property.
Home equity is the difference between your property's current market value and the amount you still owe on your mortgage and any other property related debt.
For example, if your home is estimated to be worth $750,000 and your outstanding mortgage balance is $350,000, your estimated equity is $400,000 before selling expenses and other adjustments.
A Simple Equity Estimate
Estimated home value: $750,000
Mortgage balance: $350,000
Estimated equity before selling expenses: $400,000
This is an illustrative example, not a valuation or estimate of net sale proceeds.
Equity Is Not the Same as Cash You Can Spend
Your actual proceeds will depend on the final sale price, mortgage payoff, real estate commissions and other agreed compensation, attorney fees, transfer taxes, preparation costs, and other transaction expenses that may apply.
A local real estate professional can help you estimate a realistic selling price and potential proceeds. Your mortgage lender can provide your current payoff information.
Understanding these numbers early can help you decide what price range makes sense for your next home.
3. Establish a Comfortable Budget for Your Next Home
A larger home often comes with larger expenses. Before increasing your purchase budget, look at the full cost of ownership rather than focusing only on the purchase price.
Your next home may have higher property taxes, insurance costs, utility bills, maintenance needs, and expenses related to additional space or amenities.
Build Your Budget Around the Full Picture
- Expected mortgage payment, including principal and interest
- Property taxes and homeowners insurance
- Potential mortgage insurance
- Utilities and routine maintenance
- Association fees or common charges, if applicable
- Moving expenses, furnishings, and immediate repairs
- Savings you want to preserve after closing
Ask a qualified mortgage professional to review your finances and explain the financing options available to you. A lender's maximum approval amount is not necessarily the amount you should spend.
Plan for Comfort, Not Just Qualification
The best move up purchase is one that gives you the space you need while leaving room in your budget for savings, family priorities, and the unexpected expenses of homeownership.
4. Decide Whether to Sell First or Buy First
One of the biggest questions for move up buyers is how to coordinate the sale of their current home with the purchase of their next one.
There is no single answer that works for every household. The right strategy depends on your finances, local market conditions, available inventory, and comfort with uncertainty.
Option One: Sell Your Current Home First
Selling first can help you understand how much money you will have available for your next purchase. It may also reduce the risk of carrying two mortgage payments at once.
The challenge is that you may need temporary housing or flexible arrangements if your sale closes before your next home is ready. Depending on the transaction, you may be able to negotiate timing that gives you more time to move.
Option Two: Buy Your Next Home First
Buying first may allow you to move at your own pace and avoid moving your belongings more than once. It can also help if you find a home that is difficult to replace.
However, you need to understand how you will finance the purchase before your current home sells. Carrying two properties can create financial pressure, and approval depends on your individual circumstances.
Option Three: Coordinate Both Transactions
Some homeowners work toward a coordinated sale and purchase, with dates and contract terms arranged to reduce the gap between moving out and moving in.
This approach requires communication among your real estate agent, lender, attorney, buyer, and seller. Even with careful planning, closing dates can change, so it is wise to have a backup plan.
Discuss these options before making an offer or committing to a sale. Understanding the risks in advance gives you more room to make informed decisions.
5. Choose the Right Location for Your Next Chapter
Moving up does not always mean staying in the same neighborhood. Your next purchase is an opportunity to reconsider where and how you want to live.
If you are searching in Commack, Smithtown, or elsewhere on Long Island, compare the lifestyle and ongoing costs of each area as carefully as you compare the homes themselves.
Consider These Location Questions
- How much time will you spend commuting?
- Do you want to remain close to family and friends?
- Are schools, parks, and community amenities important to your household?
- How do property taxes compare between the areas you are considering?
- Will the location still suit your needs in several years?
- Would a different property type or neighborhood provide more value for your budget?
The goal is to find a home that works for your life, not simply a larger version of the one you have now.
6. Make a Wish List Before You Start Touring Homes
More space can mean different things to different people. For one family, it may mean another bedroom. For another, it could mean a finished basement, a home office, or a larger outdoor area.
Create a list that separates your needs from your preferences. This can help you stay focused when you see attractive properties that may not actually solve your current challenges.
Your Move Up Buyer Checklist
Must Have: Enough bedrooms, a workable layout, and a location that meets your essential needs.
Would Like: A larger kitchen, extra storage, outdoor space, or a dedicated office.
Can Live Without: Features that look appealing but are not worth stretching your budget for.
Be realistic about how you use your current home. If you rarely use a formal dining room, for example, you may prefer a flexible family area instead. The best floor plan is the one that supports your everyday routines.
7. Prepare Your Current Home for Sale
Your current home deserves a thoughtful selling strategy. Its presentation, pricing, and marketing can affect how quickly it attracts buyers and the offers you receive.
Start by asking a local real estate professional to evaluate the property and identify practical steps that may help it show well.
Focus on the Details Buyers Notice
- Declutter rooms and storage areas.
- Address simple repairs and maintenance issues.
- Clean windows, floors, kitchens, and bathrooms.
- Improve curb appeal with basic landscaping and tidy entryways.
- Make rooms feel bright, welcoming, and easy to navigate.
- Discuss professional photography and a marketing plan.
Not every home needs extensive renovations before it can sell. Prioritize work that makes sense for the property's condition, likely buyer expectations, and your budget.
8. Understand the Costs Beyond the Purchase Price
A move up transaction involves costs on both sides. Planning for them early can help you avoid surprises and make a more realistic decision about your next purchase.
Potential expenses may include:
- Expenses related to selling your current property
- Attorney, title, lender, and closing expenses
- Home inspection and appraisal fees
- Moving services and temporary storage
- Immediate repairs, furnishings, or improvements
- Potential overlap between housing payments
Ask your real estate professional, lender, and attorney to help you understand the expenses relevant to your transactions. Your lender can explain financing costs, and your tax professional can discuss potential tax consequences when applicable.
9. Work With a Team That Understands Your Goals
A move up purchase often involves more moving parts than a first home purchase. You may be preparing one property for sale while evaluating another, managing financing, and coordinating several deadlines.
An experienced local real estate professional can help you assess market conditions, prepare a pricing strategy, evaluate potential homes, negotiate offers, and coordinate the timeline with the other professionals involved.
You may also need a mortgage professional to assess your borrowing options and an attorney to guide you through the legal and contract requirements.
The right team will help you understand your options, explain the tradeoffs, and keep your goals at the center of the process.
Your Move Up Plan at a Glance
Step 1. Identify what your current home is missing.
Step 2. Estimate your home's market value and available equity.
Step 3. Review your budget and financing options.
Step 4. Decide whether to sell first, buy first, or coordinate both transactions.
Step 5. Choose the locations and home features that matter most.
Step 6. Prepare your current property for the market.
Step 7. Work with your professional team to coordinate the transition.
Frequently Asked Questions
How do I know if I am ready to move up to a bigger home?
You may be ready if your current home no longer supports your needs and you can comfortably afford the next purchase. Consider your lifestyle, equity, savings, monthly expenses, and future plans before deciding to move.
Should I sell my current home before buying another one?
Selling first can clarify your available funds and reduce the risk of carrying two housing payments. Buying first may offer more flexibility if you have sufficient financing. The best approach depends on your finances, local market conditions, and tolerance for risk.
How much equity do I need to buy a larger home?
There is no single equity amount required for every move up buyer. Your options depend on your current mortgage, expected selling expenses, savings, income, credit profile, and the financing available for your next purchase. A lender can help you evaluate your options.
What additional costs should I expect when moving to a larger home?
In addition to the purchase price, consider closing costs, property taxes, insurance, utilities, maintenance, moving expenses, and possible repairs or furnishings. You may also have expenses related to selling your current property or temporarily maintaining two homes.
Can a real estate agent help coordinate selling and buying at the same time?
Yes. A real estate professional can help you plan the sale and purchase timelines, evaluate offers, negotiate terms, and communicate with the professionals involved. Closing dates can change, so it is important to discuss backup plans as well.
Your Next Chapter Starts Here
Thinking About Moving Up?
If you are ready for more space in Commack, Smithtown, or elsewhere on Long Island, Jean can help you explore your options, understand your home's potential market value, and develop a plan for your next move.
Jean Gillin
Real Estate By Jean
(631) 833 8231
jean@realestatebyjean.com
Planning Your Next Move on Long Island?
Explore resources to help you understand your real estate options during a major life transition.
Explore Life Transition ResourcesThis article is for general educational purposes only and is not mortgage, legal, tax, financial, or investment advice. Consult qualified professionals for guidance based on your personal circumstances.
Categories
Recent Posts