Smart Moves: What to Know Before Buying an Investment Property
Real Estate By Jean
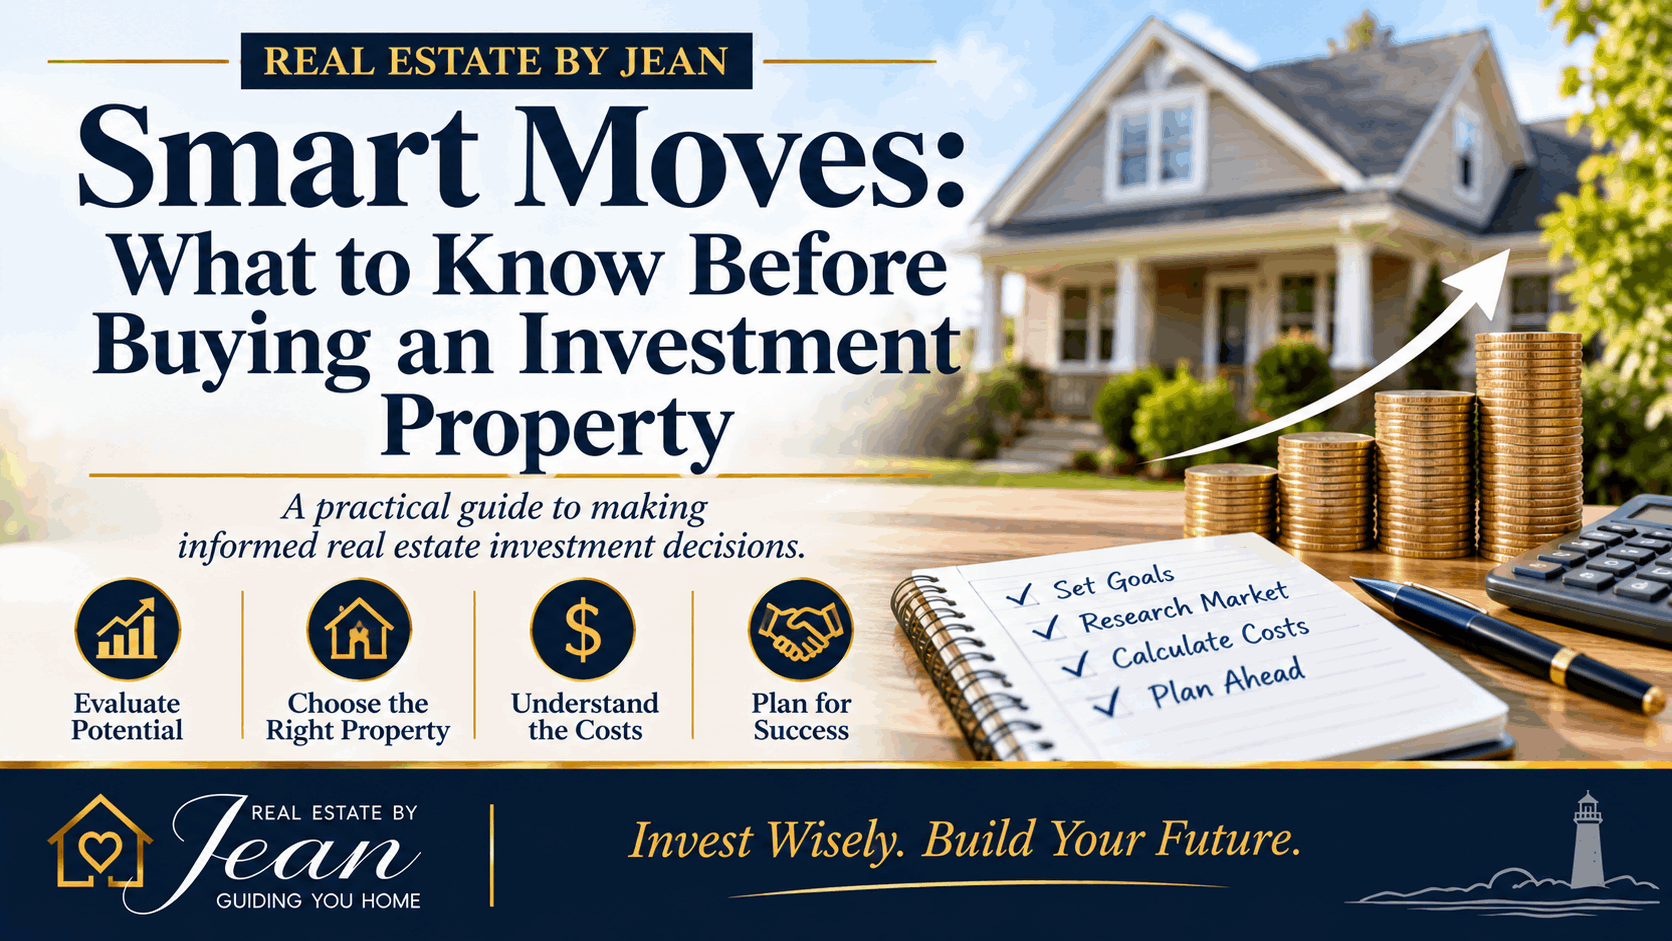
Smart Moves: What to Know Before Buying an Investment Property
A practical guide to making informed real estate investment decisions
Could an investment property be your next smart move?
Buying an investment property can be an exciting way to explore real estate ownership, build long term wealth, and potentially generate rental income. But becoming a property investor involves more than finding a home and hoping the numbers work out.
Before making a purchase, it is important to understand your goals, evaluate the local market, estimate the true cost of ownership, and prepare for the responsibilities that come with being a landlord.
Whether you are considering your first rental property or expanding an existing portfolio, a thoughtful plan can help you make a decision that supports your financial goals and personal circumstances.
What you will learn
- How to define your investment goals
- What to consider when choosing a property and location
- How to estimate rental income and expenses
- What financing and ownership responsibilities to expect
- How to prepare before making an offer
1. Start With a Clear Investment Goal
Before browsing properties, take time to decide what you want your investment to accomplish. Your goal will influence the type of property you purchase, the location you choose, your financing strategy, and how long you plan to hold the property.
Common real estate investment goals
- Monthly rental income. You may want a property that produces rental income after operating expenses and mortgage payments.
- Long term appreciation. You may be interested in owning a property that could increase in value over time. Appreciation is never guaranteed.
- Building a real estate portfolio. Your first property may be the beginning of a broader investment strategy.
- Future personal use. Some buyers consider a property that may eventually serve a personal or family purpose, although the financial and practical considerations should still make sense.
Be realistic about your timeline, available savings, tolerance for risk, and willingness to handle property management. An investment should fit your financial situation rather than create unnecessary pressure.
Smart move: Write down your main investment goal before you start looking at properties. It will help you evaluate opportunities more consistently.
2. Choose the Right Property and Location
A property's location can influence rental demand, tenant expectations, maintenance needs, and future resale potential. A home that looks attractive on paper may not be the right investment if the local rental market does not support your plan.
What should you research?
- Rental demand. Research the types of homes renters are looking for and whether there is consistent demand in the area.
- Neighborhood amenities. Consider access to transportation, employment centers, shopping, schools, parks, and other everyday conveniences.
- Comparable rental properties. Review similar properties and their advertised rents. Asking rents are not always the same as actual achieved rents.
- Property condition. Evaluate the age and condition of major systems, the roof, plumbing, electrical components, appliances, and other areas that may require attention.
- Local rules. Research zoning, rental registration, safety requirements, occupancy rules, and any restrictions that may apply to the property.
For buyers considering Long Island, it is especially important to evaluate each community individually. Purchase prices, property taxes, insurance costs, rental conditions, and local requirements can differ considerably from one area to another.
Do not rely on a neighborhood's reputation alone. Look at actual property conditions, comparable sales, realistic rental figures, and the expenses associated with owning that particular home.
3. Understand the Numbers Before You Buy
One of the most important steps in purchasing an investment property is understanding whether the potential income makes financial sense. Rental income is only one part of the equation. You also need to account for the costs of owning, maintaining, and operating the property.
Expenses to include in your budget
- Mortgage principal and interest
- Property taxes
- Landlord insurance and other applicable coverage
- Repairs, routine maintenance, and future replacements
- Utilities paid by the property owner
- Property management fees, if applicable
- Vacancy periods and tenant turnover costs
- Advertising, legal, accounting, and administrative expenses
- Association fees or other property related charges, when applicable
Look beyond the monthly rent
Imagine a property that could rent for $3,000 per month. That represents $36,000 in scheduled annual rental income if it is occupied for the entire year. However, this is not the same as profit.
You would still need to account for vacancy, operating expenses, financing costs, repairs, and other obligations. A property with attractive rental income may still have limited cash flow if its purchase price and ongoing costs are too high.
A simple investment property calculation
Annual scheduled rent
$36,000
Less vacancy allowance and operating expenses
Subtract realistic estimates for periods without tenants, taxes, insurance, maintenance, management, and other operating costs.
Less financing costs
Account for mortgage payments and other financing obligations to estimate cash flow after debt service.
Illustrative example only. The $36,000 figure is scheduled rent, not projected profit or a guaranteed return.
Understand important investment terms
Cash flow: The money remaining after collecting rental income and paying the relevant property expenses. Be clear about whether a calculation includes mortgage payments and other financing costs.
Net operating income: Rental income after operating expenses, generally before mortgage payments and income taxes.
Capitalization rate: Often called the cap rate, this is a way to compare a property's net operating income with its purchase price. It does not include mortgage financing costs and is not a guarantee of future performance.
Consider reviewing your assumptions with an accountant or financial professional. A realistic estimate is more useful than an overly optimistic projection.
4. Explore Your Financing Options
Financing an investment property may involve different requirements from purchasing a primary residence. Lenders can evaluate investment purchases differently, including the down payment, interest rate, credit profile, available reserves, and debt obligations.
Questions to discuss with a mortgage professional
- What down payment may be required for the property and loan program?
- What interest rate and loan terms are available?
- How will the lender evaluate my income, debts, and credit history?
- Will I need additional cash reserves after closing?
- Can projected rental income be considered during qualification?
- What are the estimated closing costs and ongoing loan obligations?
It is also important to keep money available for unexpected expenses. Using all your available savings for the down payment and closing costs can leave you unprepared for repairs, vacancies, or other financial surprises.
Before making an offer, obtain financing guidance based on your actual financial situation. Do not assume that the financing terms for your current home will apply to an investment purchase.
5. Be Prepared for the Responsibilities of Being a Landlord
Owning a rental property is not always a passive investment. Even when a property manager handles daily operations, the owner remains responsible for important decisions and financial obligations.
What does property ownership involve?
- Tenant communication. Responding to questions, coordinating repairs, and addressing concerns professionally.
- Property maintenance. Keeping the home in appropriate condition and addressing repair needs in a timely manner.
- Tenant screening. Following applicable laws and using consistent, lawful screening practices.
- Lease administration. Understanding lease terms, rent collection, renewals, and required notices.
- Recordkeeping. Maintaining organized records of income, expenses, repairs, communications, and important documents.
If you prefer not to manage the property yourself, a professional property manager may be an option. Management services have costs, so include those fees in your financial projections before deciding whether to hire one.
Landlords must also understand and follow applicable federal, state, and local housing laws. Before renting a property, seek qualified guidance on fair housing requirements, tenant protections, required disclosures, safety standards, and local rental rules.
6. Do Your Due Diligence Before Making an Offer
Once you find a property that appears to fit your goals, take the time to investigate its condition, financial potential, and any restrictions that could affect your plans.
Your investment property checklist
- Review comparable property sales and current market conditions.
- Research realistic rental rates for similar properties.
- Arrange a professional home inspection and review any recommended specialist evaluations.
- Check property taxes, insurance estimates, and any association fees.
- Confirm zoning and whether the intended rental use is permitted.
- Review applicable rental registration, safety, and occupancy requirements.
- Review leases, existing tenants, and any other property agreements when applicable.
- Evaluate the property's title, disclosures, and relevant documents with qualified professionals.
- Calculate your expected income, operating expenses, financing costs, and cash reserves.
Do not skip important inspections or document reviews simply because a property appears to be a good opportunity. Understanding what you are purchasing can help you avoid unpleasant surprises later.
7. Understand the Risks and Plan for the Unexpected
Every investment involves risk, and real estate is no exception. A rental property may experience vacancies, unexpected repairs, changes in market conditions, higher expenses, or difficulty finding qualified tenants.
Common risks to consider
- Vacancy risk. There may be periods when the property does not produce rental income.
- Unexpected repairs. Major systems and appliances can fail, sometimes requiring significant expenses.
- Market changes. Rental demand, property values, and financing conditions can change over time.
- Tenant related challenges. Late payments, disputes, and property damage can affect your income and responsibilities.
- Regulatory changes. Local housing laws, rental requirements, and operating costs may change.
Build a financial reserve for repairs and periods without rental income. Avoid relying on every month being fully occupied or every expense matching your initial estimate.
A strong investment plan considers what could go wrong as well as what could go right.
A thoughtful approach to investing
The Smartest Investment Starts With Preparation
Buying an investment property should be a decision supported by research, realistic financial expectations, and a clear understanding of your responsibilities.
You do not need to know every answer on your own. A real estate professional can help you understand local market conditions, compare properties, and identify questions to discuss with your lender, attorney, accountant, and other qualified advisers.
How a Local Real Estate Professional Can Help
Finding an investment property is about more than locating a home for sale. You need to evaluate whether the property, location, condition, and purchase price align with your investment objectives.
Working with a real estate professional familiar with the local market can help you:
- Identify properties that fit your investment criteria.
- Review comparable sales and neighborhood market conditions.
- Understand property features that may influence marketability and rental appeal.
- Navigate the offer and transaction process.
- Coordinate with other professionals involved in your purchase.
Real estate professionals can provide market information and transaction guidance, while mortgage, legal, tax, insurance, and property management questions should be addressed with the appropriate specialists.
Frequently Asked Questions About Buying an Investment Property
1. How much money do I need to buy an investment property?
The amount depends on the purchase price, loan program, down payment requirements, closing costs, property condition, and lender requirements. You should also have reserves for repairs, maintenance, vacancies, and unexpected expenses. Speak with a mortgage professional to understand the financing options available to you.
2. Is buying a rental property a good investment for beginners?
It can be an option for beginners who have researched the market, understand the financial responsibilities, and have a realistic plan. However, rental properties are not guaranteed to produce a profit. Evaluate the numbers, risks, and time commitment before purchasing.
3. How do I know if an investment property will be profitable?
Estimate realistic rental income and subtract expected vacancy, operating expenses, maintenance, management costs, and financing obligations. Review net operating income and potential cash flow. Consider different scenarios rather than relying on an optimistic rental estimate.
4. Should I manage my rental property myself or hire a property manager?
Self management may reduce management fees but requires time, organization, and knowledge of landlord responsibilities. A property manager can handle many daily tasks for a fee. Compare the cost of professional management with the time and responsibilities you are prepared to take on.
5. What should I look for when buying an investment property on Long Island?
Consider local rental demand, comparable rents, property taxes, insurance, purchase price, condition, maintenance needs, zoning, and rental requirements. Each community and property can have different costs and rules, so research the specific location before making a decision.
Ready to Explore Investment Properties?
Whether you are considering your first rental property or looking to expand your real estate investments, having the right information can help you take your next step with confidence.
Let's talk about your goals, the local market, and the types of properties worth exploring.
Jean Gillin
Real Estate By Jean
Phone: (631) 833 8231
Email: jean@realestatebyjean.com
Explore More Investment Property Resources
If you are considering purchasing or managing a rental property, explore this additional resource:
Real Estate By Jean
EXPERIENCE. COMPASSION. RESULTS.
This article is for general informational purposes only and is not legal, tax, mortgage, or financial advice. Investment results are not guaranteed. Consult qualified professionals regarding your individual circumstances and applicable laws.
Categories
Recent Posts