Where Will You Live in Retirement? Real Estate Options to Consider
Real Estate By Jean
Where Will You Live in Retirement?
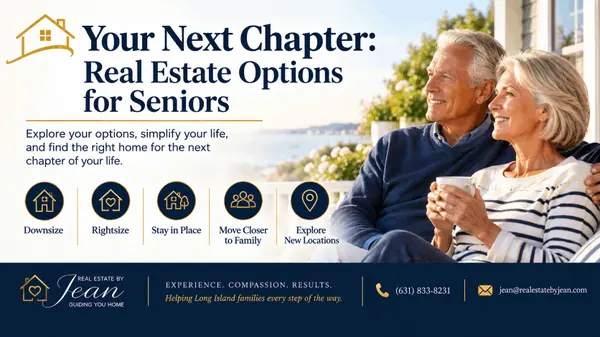
Real Estate Options to Consider for Your Next Chapter
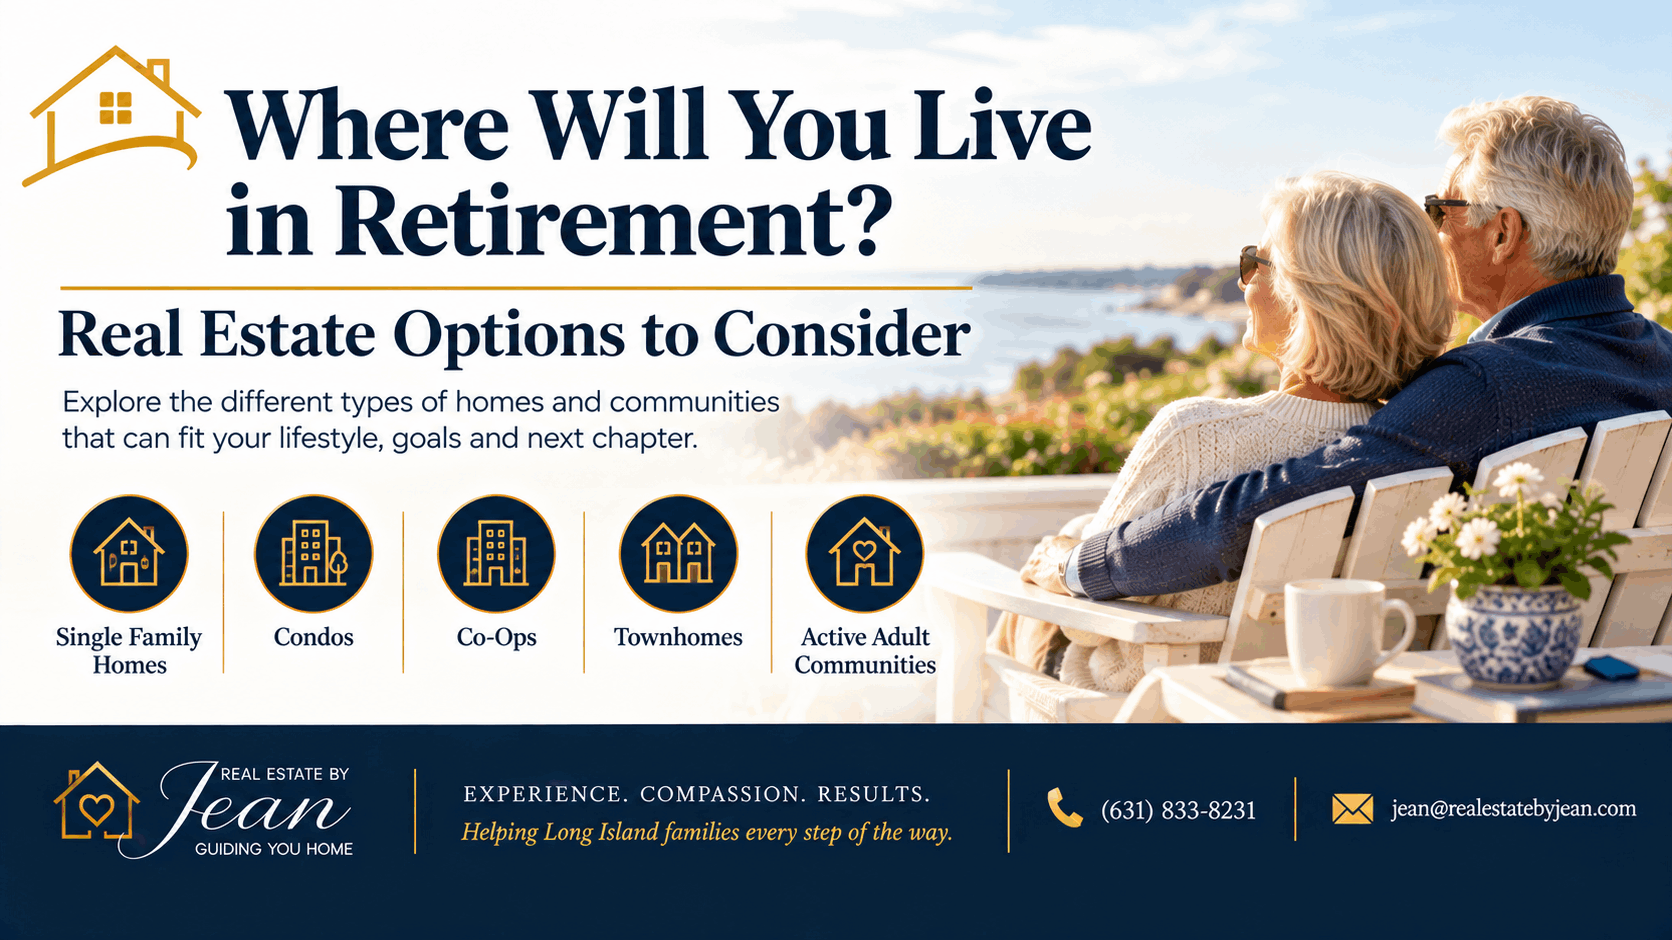
Retirement can change the way you think about your home.
The house that worked beautifully for raising a family may not be the house that makes the most sense for the next stage of life. You may want less maintenance, fewer stairs, more convenience, easier access to shopping and healthcare, or simply a home that better fits the way you live today.
For many homeowners on Long Island, the question is not simply whether to move. The bigger question is, where do you want to live when your priorities change?
There is no single right answer. Your ideal retirement home depends on your finances, lifestyle, family, health needs, desired location, and how much responsibility you want your home to require.
The best retirement move is not necessarily the smallest home. It is the home that fits the life you want to live next.
Start With Your Lifestyle, Not the Listing
Before looking at homes, think about what you want your everyday life to look like. Retirement often creates an opportunity to reconsider how much time and money you want to devote to maintaining a property.
Ask yourself:
- How much space do I actually use?
- Do I want stairs, or would one level be easier?
- How much yard maintenance do I want?
- Would I rather spend money on travel and experiences than home maintenance?
- How important is being close to family?
- Do I want to remain in my current community?
- Would I prefer more amenities and less responsibility?
These questions can help you identify the type of home that supports your retirement goals rather than simply choosing another property because it looks familiar.
Retirement Real Estate Options to Consider
There are several types of homes that may work well for retirement. Each comes with different benefits, responsibilities, costs, and lifestyle considerations.
1. A Smaller Single Level Home
For homeowners who still want the independence and privacy of a traditional house, a smaller single level property can be an appealing choice.
A smaller home may mean fewer rooms to clean, less exterior maintenance, and easier everyday living. A single level layout can also reduce the need to navigate stairs.
This may be a good fit if: You want to remain a traditional homeowner but no longer need the space of your current property.
2. A Condominium
A condominium can offer a different balance between ownership and convenience. Depending on the community, exterior maintenance and some shared responsibilities may be handled through the association.
Some condominium communities also offer amenities such as pools, fitness areas, clubhouses, parking, landscaping, and community spaces.
Consider carefully: Monthly common charges, association rules, reserves, assessments, and what those fees actually cover.
3. A Co Op
Co op living can be attractive for someone who wants less exterior maintenance and a community setting. Co op ownership is structured differently from traditional homeownership, so buyers should understand the financial and ownership requirements before making a decision.
Monthly maintenance charges, building policies, board approval, and financial requirements can all play an important role in determining whether a particular co op is a good fit.
4. A Townhome
A townhome can provide more space than some condominiums while still offering a community environment and potentially less exterior maintenance.
For some retirees, a townhome provides a comfortable middle ground between maintaining a detached house and moving into a smaller apartment style property.
5. Staying in Your Current Home
Moving is not automatically the best retirement decision. If your current home is affordable, comfortable, accessible, and located where you want to be, staying may make perfect sense.
However, it is worth looking honestly at the future maintenance requirements of the property. A home that feels manageable today may require more work as the years go by.
A Question Worth Asking
If you stayed in your current home for another ten years, would the property still support the lifestyle you want?
Think Beyond the Purchase Price
One of the most important retirement housing decisions is understanding the total cost of owning the property.
A home with a lower purchase price is not necessarily less expensive to own. Taxes, insurance, utilities, maintenance, association charges, repairs, and transportation costs can all affect your monthly and annual expenses.
Compare the Total Annual Cost
When comparing your current home with another property, consider:
- Property taxes
- Homeowners insurance
- Utilities
- Maintenance
- Association or common charges
- Expected repairs
- Transportation expenses
- Potential costs associated with accessibility
Looking at the complete picture can make it easier to understand whether a move would actually improve your financial situation.
Location Matters More in Retirement
During your working years, your home may have been chosen around commuting distance, school districts, or the needs of a growing family.
Retirement can change those priorities.
You may want to be closer to restaurants, shopping, medical services, parks, friends, family, public transportation, or community activities.
For Long Island homeowners, even a move within the same general area can create a meaningful lifestyle change. A home that is closer to the places you visit regularly can reduce driving and make everyday errands easier.
What About Selling Your Current Home First?
This is one of the biggest questions retirees face when considering a move.
Selling first can give you a clearer understanding of your available funds and may make the next purchase easier to plan. However, it can also mean finding temporary housing if the timing does not line up perfectly.
Buying first can provide more control over where you go next, but it may require additional financial flexibility.
There is no universal answer. The right sequence depends on your equity, financing, comfort level, timing, and the local housing market.
Start With Two Numbers
What could your current home realistically sell for?
What would your preferred retirement home realistically cost to own?
Create a Retirement Housing Wish List
Before you begin seriously looking at properties, create a list of what matters most.
Your Retirement Home Checklist
□ Comfortable monthly housing cost
□ Convenient location
□ Manageable maintenance
□ Comfortable number of bedrooms
□ Accessible layout
□ Space for guests if desired
□ Proximity to family and friends
□ Access to shopping and healthcare
□ Community features that support your lifestyle
Do Not Wait Until You Have to Move
One of the biggest advantages of planning ahead is having choices.
You do not have to sell your home tomorrow. You do not have to choose a new property today. But understanding your options before a major life change occurs can make the eventual decision much less stressful.
Planning early gives you time to explore neighborhoods, compare housing types, understand your finances, sort through belongings gradually, and make a decision because it is right for you rather than because circumstances forced it.
Retirement is not simply about leaving a larger house. It is about choosing a home that supports the way you want to spend the years ahead.
Frequently Asked Questions
What type of home is best for retirement?
There is no single best option. A condominium, co op, townhome, smaller single level home, or your current home may all be appropriate depending on your finances, lifestyle, maintenance preferences, and location goals.
Should I downsize before retirement or wait?
Many homeowners benefit from exploring their options before they feel pressured to move. Planning early gives you more time to compare properties, understand your finances, and decide what works best for your next chapter.
Is a condominium a good choice for retirement?
A condominium can be a good choice for someone who wants less exterior maintenance and a community setting. Buyers should carefully review common charges, association rules, assessments, reserves, and the services included with ownership.
Should I sell my current home before buying my retirement home?
It depends on your finances, equity, timing, and comfort level. Selling first can provide greater financial clarity, while buying first can give you more control over the timing of your move. A real estate professional and qualified lender can help you compare the options.
How do I know whether staying in my current home makes sense?
Consider the home's maintenance requirements, accessibility, annual expenses, location, and how well it fits the lifestyle you expect to have in the coming years. Comparing those factors with realistic alternatives can help clarify the decision.
Planning Your Next Chapter?
Let's Talk About Your Options
You do not need to have everything figured out before starting a conversation. Jean can help you understand what your current home may be worth, explore potential retirement housing options, and think through the steps involved in making a move.
Jean Gillin
Real Estate By Jean
(631) 833 8231
jean@realestatebyjean.com
Explore Downsizing and Retirement Home Options
If you are considering a smaller home, less maintenance, or a different lifestyle on Long Island, explore this helpful ICR resource for homeowners planning their next chapter.
Explore the Downsizing GuideThis article is for general educational purposes only and is not legal, tax, financial, medical, or investment advice. Real estate decisions should be considered based on your individual circumstances. Consult qualified professionals for advice specific to your situation.
Categories
Recent Posts